A look at the day ahead in European and global markets |
|
|
|
By Gregor Stuart Hunter, Asia Finance & Markets Breaking News Correspondent |
|
|
|
Federal Reserve Chair Kevin Warsh is likely to come out of Wednesday's policy decision bruised one way or another. If he stands pat, markets may revolt. If he pulls the trigger on a rate hike, the White House almost certainly will.
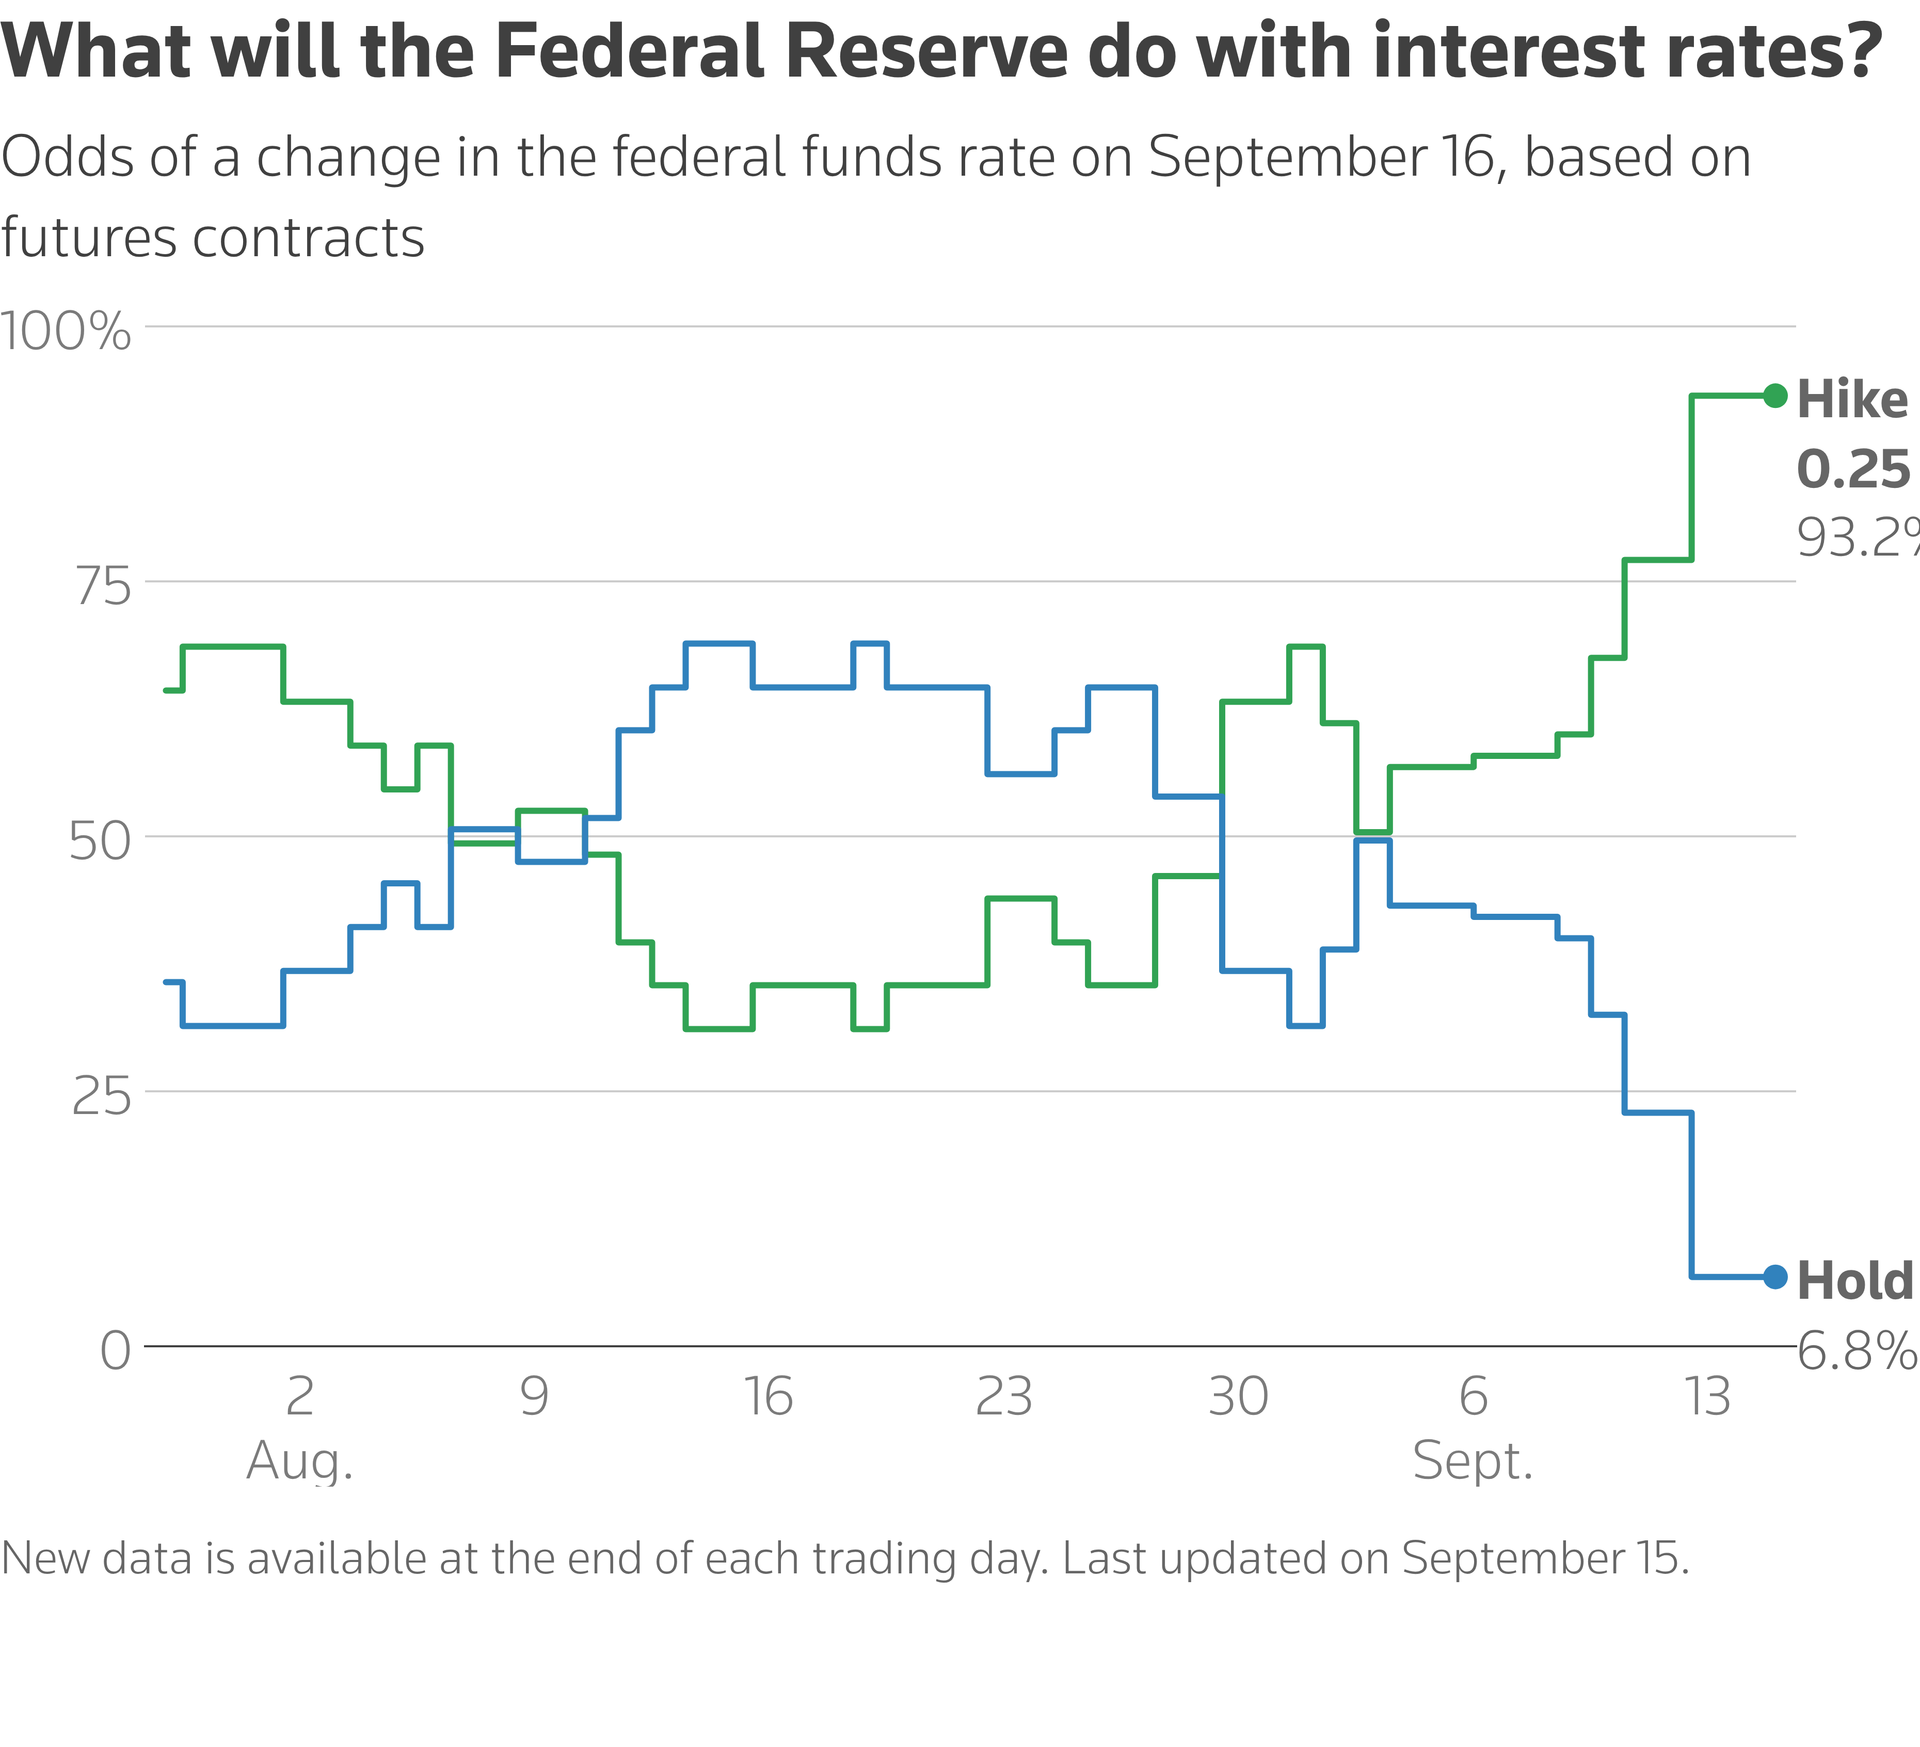
The Federal Open Market Committee has backed itself into a corner ahead of its meeting, with inflation still running above target, oil prices firmly above $100 per barrel and traders pricing a 93% chance of a rate hike - though the likely path of U.S. interest rates into next year is an open question.
|
|
|
|
U.S. President Donald Trump speaks with new Federal Reserve Chair Kevin Warsh on the day of his swearing in ceremony, in the East Room of the White House in Washington, D.C., U.S., May 22, 2026. REUTERS/Evelyn Hockstein/File Photo |
A hike carries its own risks. President Donald Trump has repeatedly pushed for lower borrowing costs and last month, he even threatened to cut off trade with countries running surpluses against the U.S. if the Fed failed to lower rates. Whether this is all bluster remains anyone's guess.
Still, there has been some reprieve for markets on Wednesday - the yield on the U.S. 10-year Treasury bond has nudged lower after breaking above the 5% mark a day earlier. Oil prices also stepped back, with an unexpected rise in U.S. crude inventories taking some heat out of the rally. Brent crude slipped 0.9% to $107.82 a barrel.
|
Graphics are produced by Reuters |
|
|
|
Fragile investor confidence |
But with other major central banks, including the Bank of Japan, also poised to tighten policy this week, investor confidence is proving skittish.
Stocks managed a cautious rebound after several false starts. MSCI's broadest index of Asia-Pacific shares outside Japan (.MIAPJ0000PUS) was up 0.6%, the Nikkei 225 (.N225) added 0.4% and U.S. S&P 500 e-minis were up 0.2%.
The tentative optimism carried into Europe, with the pan-region Euro Stoxx 50 futures , German DAX futures , and FTSE futures all up 0.3% in early trading.
Elsewhere, digital assets extended losses after the U.S. Senate voted on Tuesday against comprehensive cryptocurrency legislation backed by Trump. Bitcoin slid 0.1% to $75,816.24, while ether slipped 0.2% to $2,403.27. |
|
|
|
Key developments that could influence markets on Wednesday: |
-
UK: CPI, RPI and PPI for August
- Euro Zone: Industrial production for July and labour costs for Q2
- Debt auctions: Germany: 21-year and 30-year government debt
|
|
|
|
Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias.
|
|
|
|
| |
|
|
|
Morning Bid is sent every weekday morning. Think you | | | |
|
|
|