
|


Over the past five articles, we’ve taken a deep dive into the macro environment and the AI buildout.
We’ve looked at the stressed consumer, the massive CapEx spending, and the physical limits of the power grid.
Today, we’re going to talk about how this all could unwind, and where I actually want to invest.

 |
Let’s do a quick recap of how we got here.
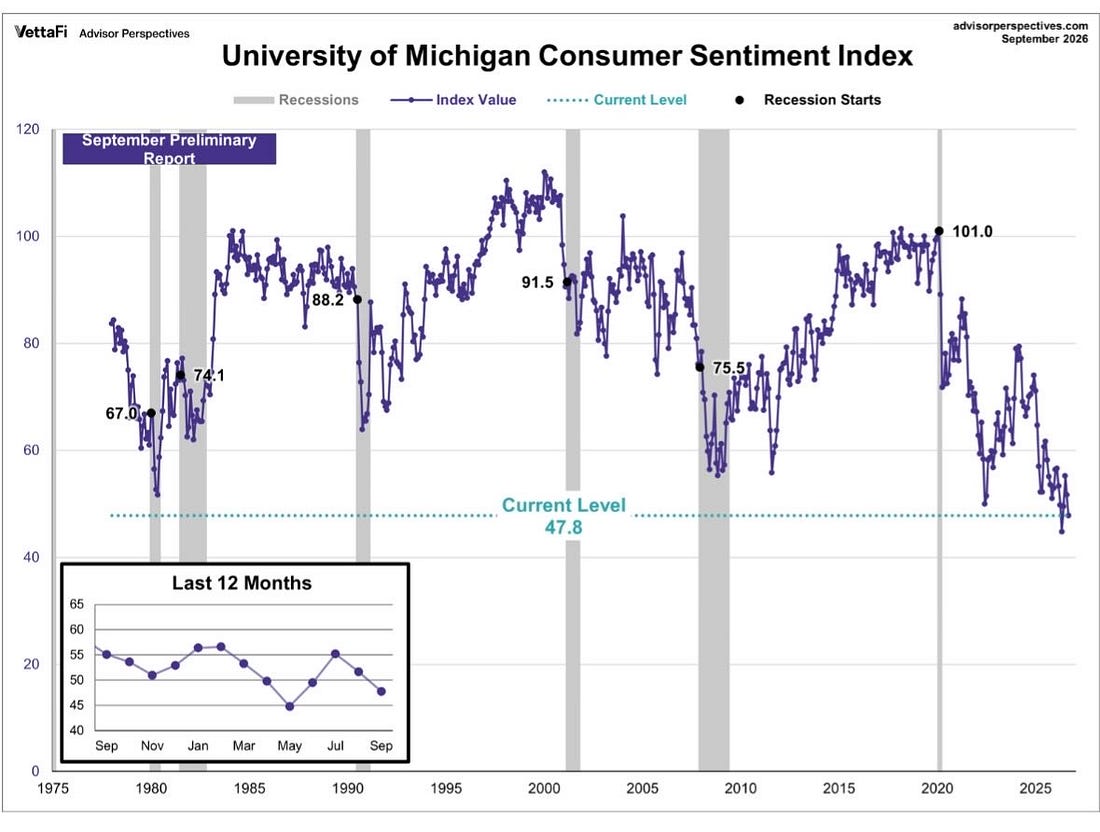
In Part 1, we looked at the consumer. Wages haven’t kept up with inflation, savings are dropping, and the average stock in the S&P 500 is actually struggling.
 |
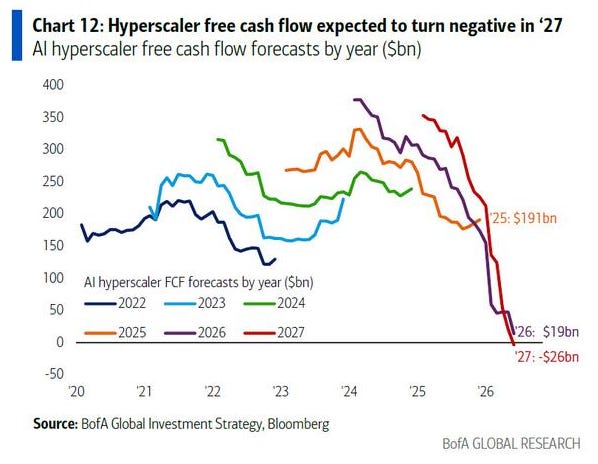
In Part 2, we looked at AI CapEx. Tech companies are spending trillions, taking on huge depreciation expenses, and turning into capital-intensive businesses.
 |
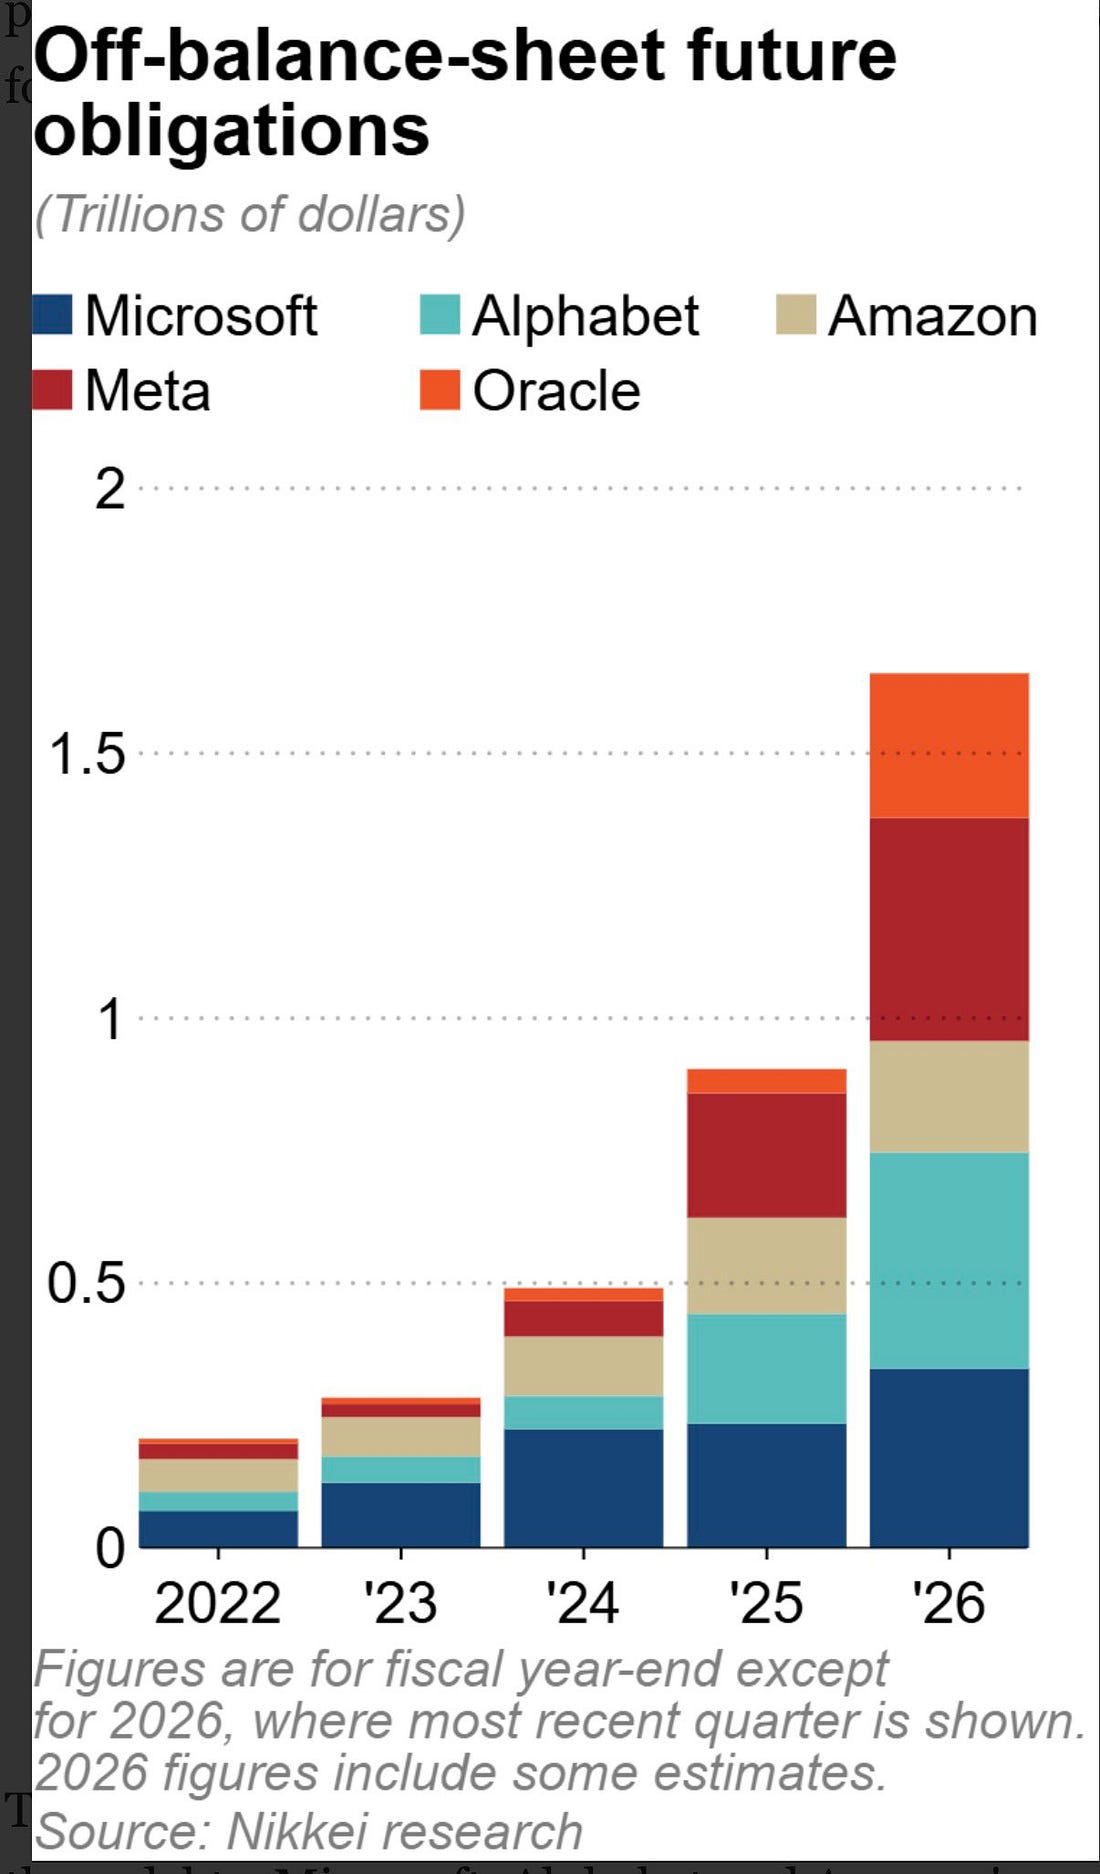
In Part 3, we looked at the financing. We saw circular revenue loops, off-balance-sheet debt, and the very real possibility of phantom demand.
 |
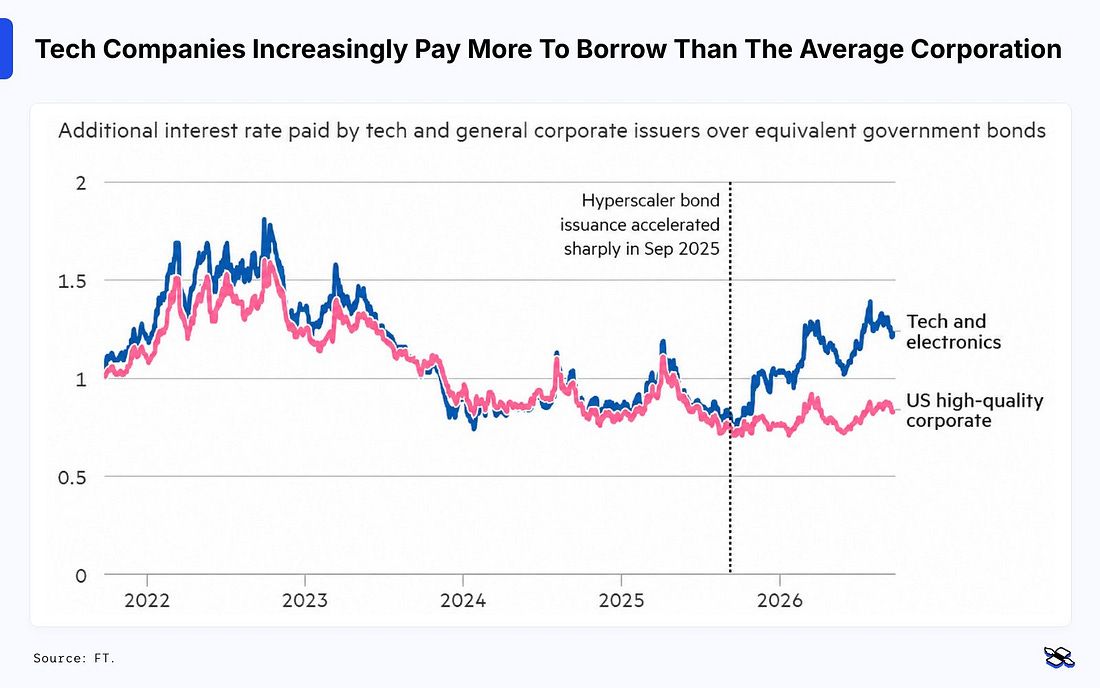
In Part 4, we looked at the physical world. Data centers need massive amounts of power and equipment that don’t exist yet, and the bond market is demanding higher yields to fund it all.
 |
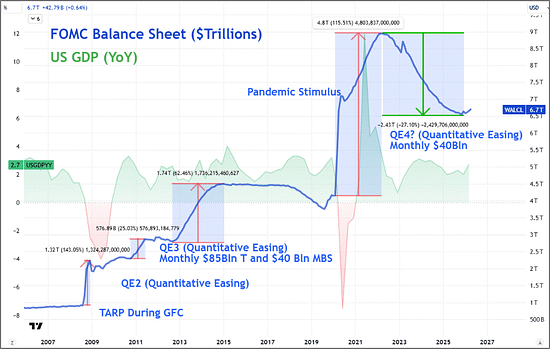
In Part 5, we looked at the stock market itself. Passive index funds have pushed the biggest tech names to huge valuations, and the U.S. government has too much debt to step in with a bailout if prices fall.
 |
What Now?
So what if this cycle breaks?
Every massive infrastructure buildout so far has led to overcapacity and a bust.
This one could be different, but I’m not betting on it.
If the AI buildout follows past history, here's what happens: